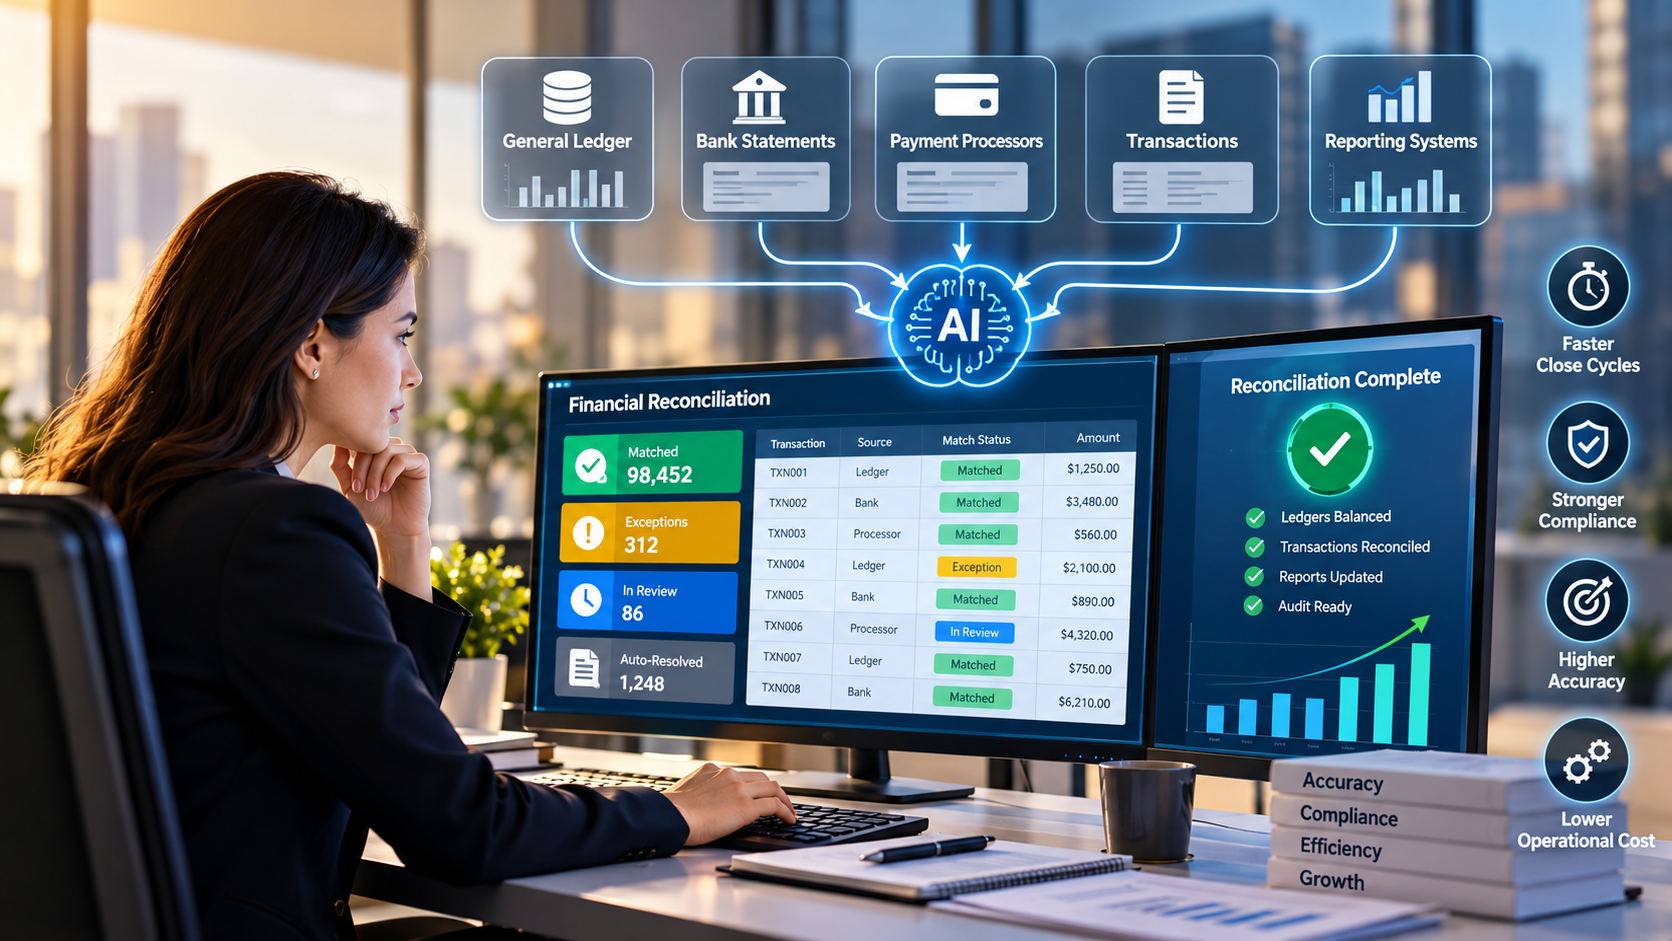
Reconciliation automation uses rules, data integration, and controlled AI to match records between the general ledger, bank statements, payment processor reports, and subledgers. Clear matches are cleared automatically, while exceptions are classified and routed to a named owner. Final balances still need human review and sign-off.
Ask a controller what slows down the month-end close, and reconciliation usually comes up first. Someone exports the bank file, another person exports the general ledger, and a third person spends hours matching them line by line. A few items do not match. Some are timing differences that will clear next week. Others are real errors that need an investigation, a correction, or a call to the bank.
This work is important, and it is repetitive. It is also one of the best places to apply automation in financial services, because the rules are often clear and the volume is high. Yet many firms still run reconciliation through spreadsheets, email, and manual uploads, which makes the process slow, hard to audit, and dependent on a few experienced people.
If you want help scoping this work, our AI automation services are a practical starting point. This article covers what reconciliation really involves, the business problems it creates, what the latest US payment data suggests about its growing scale, and how to design an automated process that is accurate, explainable, and controlled. It ends with a practical implementation plan, the metrics to track, and the questions to ask before choosing a partner or a platform.
How reconciliation automation works
- Import the sources. Bank files, processor settlement reports, and ledger extracts are loaded for the same period.
- Standardize the data. Formats, dates, cut-off times, and reference codes are aligned so records can be compared.
- Match in tiers. Exact matches clear first, then tolerance, grouped, and known-pattern rules handle the rest.
- Route the exceptions. Unmatched items are classified, assigned an owner, and given a due date.
- Report and sign off. Reconciled balances feed reporting, with an audit trail and a human approval on final balances.
What reconciliation means in practice
At its simplest, reconciliation compares two sources of truth and explains the difference. In financial services, those sources include the following:
- The general ledger, the company's own record of transactions and balances
- Bank statements and bank feeds, which show cash movements at each institution
- Payment processor reports, which show card, ACH, wire, and digital payment activity
- Subledgers, such as accounts receivable, accounts payable, loans, or customer balances
- Intercompany records, where entities within a group must agree with each other
- Reporting systems, which depend on the reconciled figures for regulatory and management reports
Each comparison follows the same pattern. Records are matched by reference, amount, date, and counterparty. Matches are cleared automatically. The remaining items are classified as timing differences, fees, refunds, duplicates, or true exceptions. The classified items are either resolved or escalated, and the final balance is signed off.
The challenge is volume and variety. A single institution may process large numbers of transactions each day, across many channels, with different formats, cut-off times, and fee structures. Matching them by hand is slow, and the error rate rises as the volume grows.
The scale of noncash payments
The volume behind reconciliation has grown steadily. The Federal Reserve's 2025 Triennial Payments Study released initial findings on July 1, 2026. It reports that the total number of noncash payments made by consumers and businesses increased to 236.6 billion in 2024, and that the number of noncash payments more than tripled since 2000 (Federal Reserve press release).
The mix of payments is also changing. The ABA Banking Journal's coverage of the study reports that debit cards accounted for 64% of all card payments by number in 2024, down from 68% in 2021. Credit card payments grew faster than debit for the first time in almost a decade. Checks continued their long decline, falling to 9.2 billion by number in 2024. ATM withdrawals also kept dropping, from 5.2 billion in 2015 to 3.4 billion in 2024 (ABA Banking Journal, July 2026).
These figures matter for reconciliation for three reasons:
- More transactions mean more matches. Growth in the count of payments increases the number of records that must be matched each period.
- The channel mix is shifting. Card and digital payments settle differently from checks and cash. Each channel has its own timing, fees, and reporting format, so the matching rules must cover more than one pattern.
- Reconciliation must keep up with change. A process built around last year's mix of payments will break when a new channel grows or a processor changes its file format.
The Federal Reserve describes the study as an ongoing effort to estimate aggregate trends in noncash payments, and it notes that additional details will follow as analysis is completed (Federal Reserve Payments Study). The figures are preliminary, but the direction is clear: more payments, across more channels, to reconcile.
The business problems reconciliation creates
Reconciliation is more than a bookkeeping task. When it is slow or unreliable, several business problems follow.
Delayed close. If reconciliations are not complete, the month-end close slips, and management reports arrive late. Late numbers reduce the time leaders have to act on them.
Unexplained differences. Items that sit unexplained for weeks can hide errors, fraud, or duplicate payments. Each unexplained item is also a question an auditor may ask.
Cash visibility gaps. Treasury teams depend on accurate cash positions. If the ledger lags the bank, the business may hold too much idle cash or miss an opportunity to invest it.
Regulatory and audit pressure. Regulated firms must show that their records are accurate and that exceptions are handled. Weak reconciliation controls can create findings, remediation work, and reputational risk.
Key-person risk. When a few experienced staff hold the knowledge of how each difference is resolved, the process depends on them. Absence, turnover, or burnout can disrupt the close.
Hidden cost. Skilled accountants spend time on routine matching instead of analysis, controls, and forecasting. The cost is not only the hours spent, but also the decisions that do not get made.
What automation can and cannot do
Automation is most effective for high-volume, rule-based matching. A well-designed system can read bank and processor files, normalize the formats, match transactions using reference numbers, amounts, dates, and counterparties, and clear the items that meet the rules. It can also flag items that do not match, group them by likely cause, and route them to the right owner.
Automation is less suitable for judgment-heavy items. A disputed payment, an unusual intercompany balance, a suspected duplicate, or an error that requires a bank inquiry needs a person to investigate. The aim is not to remove accountants from reconciliation. It is to let them focus on the items that need expertise.
Artificial intelligence can add value in two places. It can suggest matches when reference numbers are missing or inconsistent, and it can help classify exceptions based on past resolutions. Both uses need clear rules, human review, and an audit trail. An AI suggestion should never post an entry without a control that a person can check.
Design the reconciliation process before you automate it
Automating a broken process only makes errors happen faster. Before building anything, document the process as it runs today.
Map each reconciliation: the sources, the frequency, the owner, the matching rules, the typical exception types, and the sign-off. Note where people rely on tribal knowledge, such as "that fee always shows up on the second day" or "this processor reports refunds under a different reference." Those notes become rules in the automated process.
Then set the design principles that will guide the build:
- Every match has a reason. The system should record which rule matched each item, so the result can be explained to an auditor.
- Every exception has an owner. Unmatched items should go to a named person or queue, with a due date.
- Every rule is versioned. When a matching rule changes, the change should be recorded, approved, and dated.
- Every automated action is reversible. A cleared item should be able to be reopened, with a log of who changed it and why.
- Human sign-off remains. The final balance and any manual adjustments should be approved by a person with the right authority.
These principles protect the business as much as they speed up the work.
Step 1: Choose the first reconciliation
Start with one reconciliation that is high volume, well understood, and has clear rules. Bank-to-ledger reconciliation for a single operating account is often a good first candidate. Card settlement reconciliation for one processor can also work well.
Avoid starting with the most complex reconciliation, such as a multi-entity intercompany process with many exceptions. Build confidence first, then extend the approach.
Record the baseline before you change anything. Measure the hours spent, the number of items processed, the exception rate, the time to close, and the number of unexplained items at the end of each period. The baseline is how you will prove the value later.
Step 2: Gather and standardize the data
Reconciliation depends on data that arrives in different formats, at different times, from different systems. The first technical task is to make that data consistent.
Bank files. Collect statements and transaction feeds in a consistent format, with clear dates, amounts, descriptions, and references. Note the cut-off times, because a transaction posted after cut-off belongs to the next day.
Processor reports. Settlement reports often show gross amounts, fees, chargebacks, and refunds on separate lines. Map each line to the ledger account it affects.
Ledger extracts. Pull the general ledger for the same period, with account codes, posting dates, references, and descriptions. Confirm that the ledger extract is complete before matching begins.
Reference data. Keep a current list of bank accounts, processor identifiers, entity codes, and fee types. Many matching problems come from stale reference data rather than from the matching logic itself.
Validate the data before matching. Check totals, row counts, and date ranges against the source. For the data foundation behind this step, see our data warehousing and analytics services. A file that is missing a day should be caught before the match starts, not after the exceptions pile up.
Step 3: Build the matching rules
Matching rules tell the system how to compare records. A strong rule set usually works in tiers, from the most precise match to the least precise.
Tier 1: exact match. Match on a unique reference number, the same amount, and the same date. This tier should clear the majority of items.
Tier 2: tolerance match. Match when the reference and amount agree but the date differs within an agreed window, such as a settlement delay over a weekend. Set the tolerance by account and by channel, and document the reason.
Tier 3: grouped match. Match a batch of ledger entries to a single bank line, such as a daily deposit that combines many customer payments. Group rules should check that the totals agree and that the batch is complete.
Tier 4: known patterns. Match recurring items, such as a processor fee that always posts as a separate line. These rules reduce noise, but they should be reviewed regularly, because processor formats change.
Each rule should have an owner, a version number, and a test case. Before a rule goes live, run it against past periods and check that it matches the items the team would have matched by hand.
Step 4: Handle exceptions with discipline
Exceptions are where reconciliation earns its keep. An unmatched item may be a timing difference, a fee, a refund, a duplicate, a bank error, or a real problem. The exception process decides how quickly each one is resolved.
Create an exception classification with a short list of types, such as timing, fee, refund, duplicate, missing entry, bank error, and unknown. Let the system suggest a type based on the rules and past outcomes, and let a person confirm it.
Assign each exception an owner and a due date. Group exceptions by age, so the oldest items are visible. Set escalation rules, such as moving an item to a senior reviewer after a set number of days, or when the amount exceeds a limit.
Keep a resolution log. Record what was done, who did it, and why. This log is the best source of evidence for auditors, and it becomes a training set for better rules over time.
Step 5: Connect reconciliation to reporting
Reconciled balances feed financial statements, management reports, and regulatory filings. The connection between the two should be clear and controlled.
Build a reconciliation status view that shows, for each account, whether the balance is reconciled, the amount of open exceptions, and the date of the last sign-off. Reporting teams should be able to see which numbers are final and which still have open items.
Avoid manual copying of balances into reports. Where possible, pass the reconciled figures from the reconciliation system to the reporting layer through a controlled interface. Log every change to a reported number, and keep the prior version for reference.
Where a report depends on a reconciliation that is not yet complete, show the status clearly. A number labeled "preliminary, reconciliation open" is more honest than a number that looks final but is not.
Step 6: Protect the controls
Reconciliation is a control, not only a process. Its value depends on the controls around it.
Segregation of duties. The person who posts an entry should not be the only person who reconciles it. The person who approves a rule change should not be the one who builds it.
Access control. Limit who can change matching rules, reference data, and tolerance settings. Review access regularly.
Audit trail. Record every automated match, every manual clearing, every rule change, and every sign-off. The trail should be complete enough for an auditor to follow any item from source to report.
Change management. Test every rule change before release. Keep the previous version available, so a faulty change can be rolled back quickly.
Monitoring. Watch for failed file loads, sudden changes in match rates, growing exception ages, and unusual amounts. An alert is more useful than a surprise at month-end.
Data security matters as well. Financial data is sensitive, so transfers should be encrypted, access should follow the principle of least privilege, and retention should follow your policy and legal obligations. Confirm where data is stored and processed before any vendor receives a file.
Step 7: Test before you rely on it
Testing should cover normal cases and the cases that go wrong. A useful test plan includes the following:
- A full month of past data, to compare automated results with the manual reconciliation
- A late bank file, to confirm the system handles a missing day
- A duplicate processor report, to confirm duplicates are caught
- A refund that arrives in a different period from the original sale
- A foreign currency item, if the business handles multiple currencies
- A rule change, to confirm the audit trail and the rollback process work
- A simulated outage, to confirm the team knows how to recover
Document the results. Share them with the controller, the internal audit team, and anyone who signs off on the close.
Step 8: Run in parallel, then cut over
Run the automated reconciliation alongside the manual process for at least one full close. Compare the results item by item. Investigate every difference. Some differences will reveal errors in the automation. Others will reveal errors in the manual process, which is a valuable finding in itself.
When the results agree and the team trusts the exception handling, cut over in stages. Move one account at a time, and keep the manual fallback available for the first few periods.
Track adoption after cut-over. Check whether people are working the exception queue, whether overrides are being recorded, and whether the rules are being maintained.
Step 9: Build a maintenance routine
Reconciliation is never finished. Banks change file formats, processors add fee types, and business lines launch new products. A maintenance routine keeps the process accurate.
Review the matching rules each month and each quarter. Check the match rate by rule, the exception rate by type, and the oldest open items. Retire rules that no longer match anything, and add rules for new patterns that appear in the exception log.
Keep the reference data current. Confirm that new bank accounts, processor identifiers, and entity codes are added before they generate transactions.
Illustrative example: a regional lender's card settlement reconciliation
The following scenario is hypothetical. It shows how the approach can work in practice. It does not describe a specific institution or result.
Imagine a regional lender that processes card settlements from several merchant partners. Each month, its finance team reconciles daily settlement files against the general ledger and the operating bank account. The work is repetitive, and the team spends several days each month on it.
The lender starts with one settlement stream. The team documents the current process, collects two months of past files, and builds tiered matching rules. The first tier matches on reference and amount, the second allows a weekend timing window, and the third handles daily batches that combine many customer payments.
The automated process runs in parallel for one close. The team compares the results item by item. They find that the automation matches more items than the manual process, but it misses a refund pattern that changed when one partner updated its file format. The team fixes the rule, records the change, and reruns the test.
After cut-over, exceptions are grouped by age and type. Most timing differences clear within a day. The team reviews the remaining items in a short daily session. Senior reviewers handle the unusual items, and the resolution log becomes the basis for new rules.
The lesson is that the value comes from the design, the testing, and the controls, not from the matching engine alone.
Fit reconciliation into the close calendar
Reconciliation is not a one-time project. It runs on a calendar, and the calendar sets the deadlines that automation must meet. Map each reconciliation to the close schedule, from the first day after period end to the final sign-off.
A typical pattern looks like this. Bank and processor files arrive in the first business days. Automated transaction matching runs as each file lands, so most items are cleared before the team starts its review. The team works the reconciliation exceptions queue in priority order, starting with the oldest and largest items. Subledger teams clear their own open items. Reporting teams receive a status view, and they know which balances are final.
Set internal deadlines before the close begins. For example, decide that all bank-to-ledger reconciliations for operating accounts must be complete by a fixed day, and that exceptions older than a set number of days require a written explanation. Deadlines give the automation a target and give the team a way to see when the close is at risk.
Plan for the days that break the pattern. Holidays, system outages, late bank files, and processor cut-over dates all affect the calendar. A good process has a fallback that is tested in advance, so the close does not stall when one file arrives late.
Build a sign-off checklist for each reconciliation
Before a reconciliation is signed off, the reviewer should confirm a short list of points. A standard checklist makes the review consistent and easy to audit:
- All source files for the period are loaded, and the totals match the source reports.
- The ledger extract is complete, with no missing dates or accounts.
- Automatic matches were reviewed for the largest items and for any new rule.
- Every open exception has an owner, a due date, and a classification.
- Timing differences are expected to clear in the next period, and that expectation is documented.
- Manual adjustments have approval and a reason.
- The final balance agrees to the bank or processor statement, with any difference explained.
- The reconciliation status has been updated for reporting.
A checklist does not replace judgment. It makes sure the judgment is applied to the same points every period, which is what auditors expect to see.
Measuring success
Track the measures that show whether reconciliation is faster, more accurate, and better controlled:
- Close time. How many days from period end to a signed-off reconciliation.
- Automatic match rate. The share of items cleared by rules without manual work.
- Exception rate and age. How many items are open, and how long they have been open.
- Unexplained differences at period end. The amount left unexplained after review.
- Effort per period. Hours spent by the team on reconciliation, before and after automation.
- Audit findings. Any findings related to reconciliation, and how quickly they close.
Read these measures together. A high automatic match rate is only good if the matches are correct and the exceptions are handled. A fast close is only good if the balances are right.
Common mistakes to avoid
- Automating a process that is not documented. Write the process down first, including the informal rules.
- Starting with the hardest reconciliation. Build confidence on a simpler one.
- Using tolerance settings that are too wide. Wide tolerances hide real errors.
- Ignoring reference data. Stale account and processor codes cause many avoidable exceptions.
- Letting the automation post without review. Keep human sign-off for final balances and adjustments.
- Skipping the parallel run. A parallel run is the best way to find errors before they reach reporting.
- No maintenance plan. Processors and banks change formats, and the rules must change with them.
Frequently asked questions
What is financial reconciliation automation? Financial reconciliation automation uses rules, data integration, and sometimes AI to match records between the general ledger, bank statements, payment processor reports, and subledgers. Items that match clearly are cleared automatically. Items that do not match are classified and routed to the right person. Final balances still need human review and sign-off.
How does automated bank reconciliation work? The system imports bank statements and the general ledger, standardizes their formats, and matches transactions using reference numbers, amounts, dates, and counterparties. It applies tiered rules, from exact matches to grouped and tolerance-based matches. Unmatched items are grouped by likely cause and sent to an owner for resolution, with a full audit trail.
Can AI help with ledger reconciliation? Yes, in limited and controlled ways. AI can suggest matches when reference data is inconsistent and can help classify exceptions based on past resolutions. Its suggestions should be reviewed by a person and recorded in the audit trail, and it should not post entries on its own.
What data is needed to automate reconciliation? You need bank statements or feeds, general ledger extracts for the same period, processor settlement reports, and current reference data for accounts, processors, and entities. Clean and complete files are essential, so the system can detect missing days and duplicate reports before matching begins.
How do you keep an automated reconciliation audit-ready? Keep a complete audit trail of every automated match, manual clearing, rule change, and sign-off. Use segregation of duties, limit who can change rules, test changes before release, and keep previous rule versions available for rollback. Document the testing results and share them with internal audit.
How long does it take to automate reconciliation? The timeline depends on the number of accounts, the complexity of the data, the quality of the source files, and the testing required. A focused pilot on one high-volume reconciliation is usually the fastest way to prove value. A realistic timeline should be set after a discovery assessment of the specific systems involved.
Next steps
If your team is reviewing how to automate reconciliation, start with one high-volume account and a documented baseline. For more on how we support financial services organizations, read about our work for financial services organizations.
Discuss Your Financial Reconciliation Automation Requirements